Hotels in transition: what a special situation really requires
When a hotel passes between lenders and shareholders, the problem is rarely the building. It is alignment. I use a case I am working on as a thread to explain what is really needed.
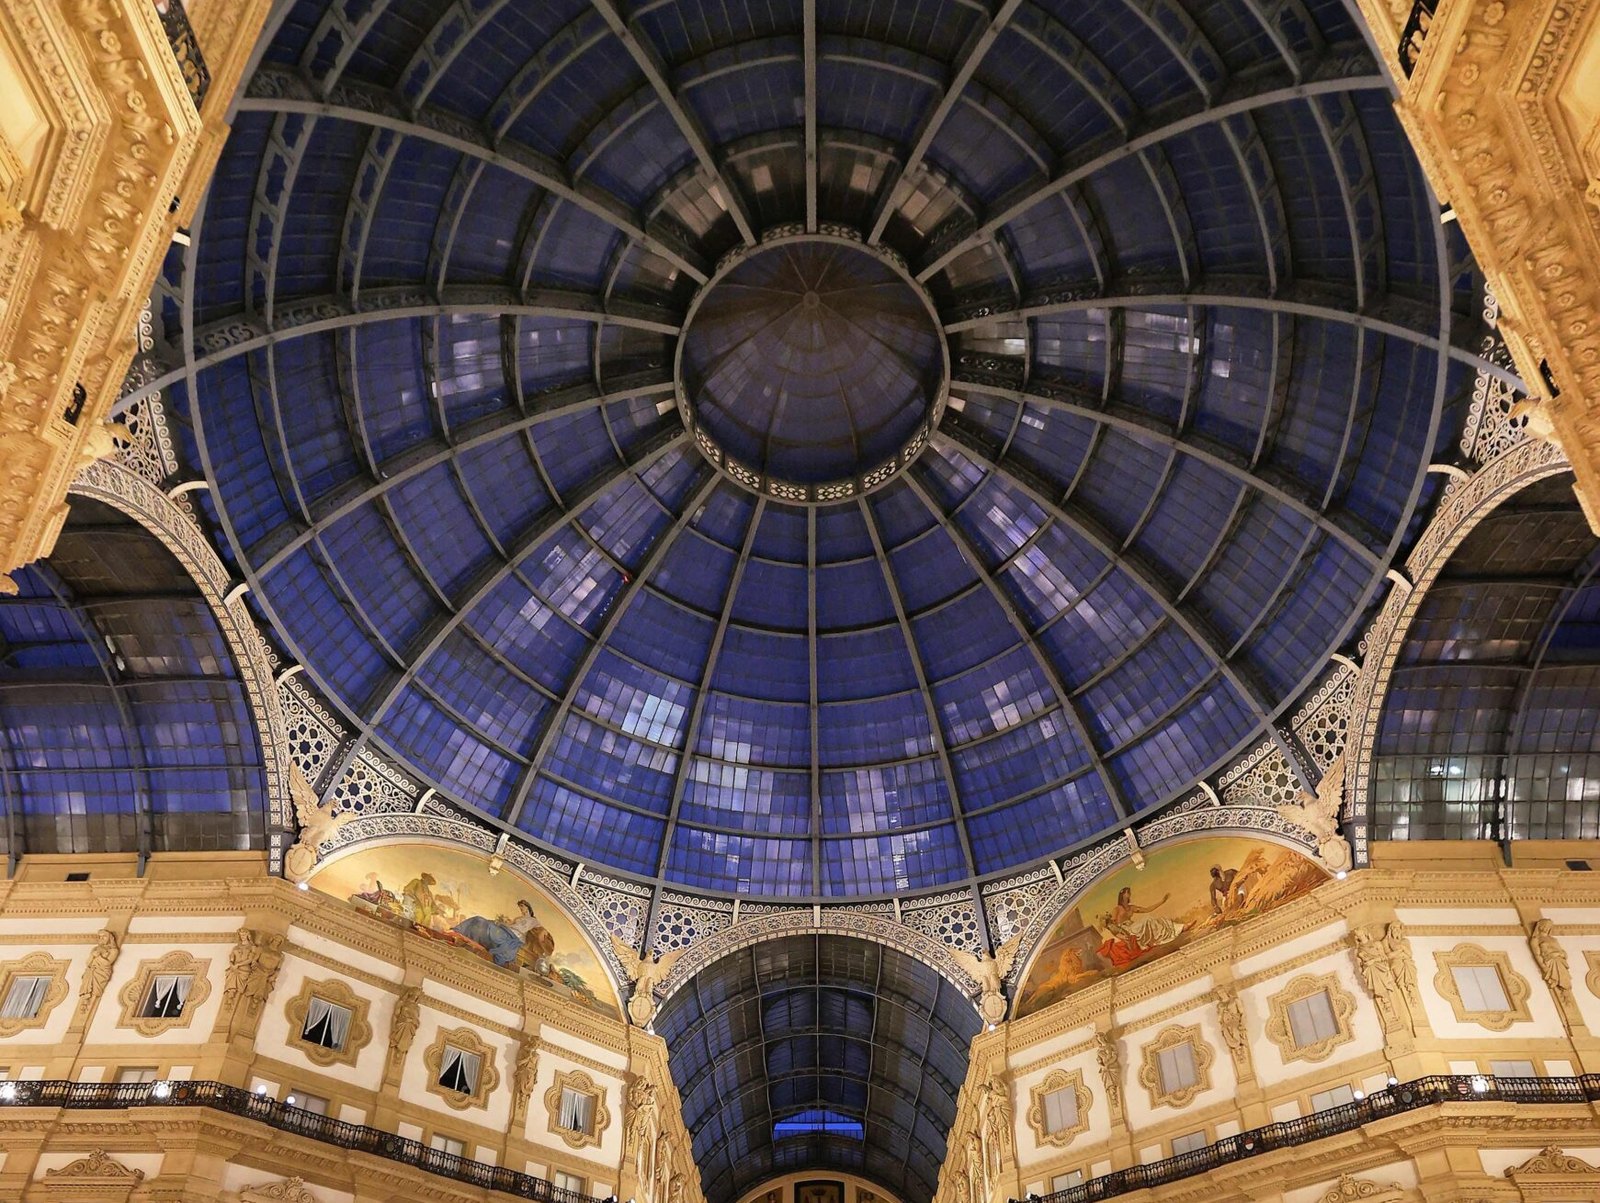
I am working on a hotel in a major city in northern Italy. The building is well located, the brand is recognised, the demand is there. Yet the hotel is stuck in transition: the lender wants to exit, the shareholders have different visions, the operator is waiting for direction. Each party is right from its own point of view. None, on its own, can unlock the situation.
It is the typical pattern of a hotel special situation. The value is there, but it is held back by a structure that no longer works.
Aligning those at the table
In a hotel there are at least four parties: the lender, the owner, the operator, the brand licensor. Each has a contract, a time horizon and a different idea of success. The lender looks at repayment. The shareholders look at the value of their equity. The operator looks at operating margins. The brand looks at standards.
The first task is to make these positions explicit. I meet each party separately, read the contracts, and work out what is genuinely negotiable and what is not. Only then do I propose a common solution. A special situation is resolved when each party sees in the proposal an outcome better than its own alternative.
The deadlock often stems from a contractual detail: a veto right, a clause in the hotel management agreement, an obligation to the brand for upgrade works. Identifying it early avoids months of negotiation on the wrong point.
Understanding the debt, not just measuring it
Knowing the amount of the debt is not enough. You need to understand its nature: security, clauses, covenants breached or at risk, maturities, any sales to specialist investors. A loan classified as unlikely-to-pay offers different room from one already classified as a bad loan. A servicer has different constraints from a bank. A bank that has already written down the position has different flexibility from an investor that bought the loan at a discount with a precise recovery target. Understanding this logic is the basis of any realistic proposal.
This analysis shapes the proposal to the lender: a partial repayment with new capital, a rescheduling of maturities, an orderly sale of the position. The choice depends on the numbers, not on preferences.
In a hotel in transition, value is lost above all in the time that nobody decides to use.
A credible business plan
No lender and no investor accepts a restructuring without a business plan. The plan must say what changes in the operation: positioning, sales channels, costs, maintenance capex, energy efficiency. It must rest on assumptions that can be verified and benchmarked against the market. It must also say what happens if the assumptions do not materialise. That is why I build it on several scenarios, prudent, base and favourable, with corrective levers for each. A lender places more trust in a plan that shows its own limits.
A credible plan takes people into account. The team at a city hotel is often its competitive advantage. A badly handled change of ownership scatters skills and trust. An orderly transition protects them, and with them the quality of service and the livelihoods of many families.
New capital, with a plan
New capital comes only after these steps. It comes from authorised partners, such as authorised Italian asset managers (SGRs), fund managers and banks, through regulated structures such as a real estate fund or a special purpose vehicle. Capital without a plan buys time. Capital with a plan builds a future.
The brand should also be involved early. A change of ownership can be an opportunity to review standards and upgrade timelines, or to reposition the hotel under a brand better suited to its market.
My role is one of strategic advice: building alignment, preparing the dossier, coordinating the professionals and bringing the right parties to the table. Investment decisions remain with those authorised to make them.
If you are a shareholder, lender or operator of a hotel going through a transition and you recognise this pattern, we can discuss it in a confidential conversation.
Views expressed are personal. This article does not constitute an offer, a solicitation to invest or investment advice.